
The 28 October 2026 Budget didn’t change stamp duty, so buying a home in Shropshire costs the same in stamp duty as it did before.
Three things did change for buyers. A new scheme, Your First Home, will let first-time buyers buy a new-build home with a 2.5% deposit. The Lifetime ISA penalty on homes above £450,000 has been cut from 25% to 20%. And rental income will be taxed at higher rates from April 2027, which matters if you’re thinking of keeping your old home and letting it out.
Here’s what each one means, and what it means if you’re looking at a new home in Shropshire.
Budget 2026 for home buyers: the key changes
- Stamp duty hasn’t changed. The rates and the first-time buyer relief are the same as before.
- A new scheme, Your First Home, will let first-time buyers buy a new-build home in England with a 2.5% deposit and a government equity loan. Applications open in February 2027.
- Tax on rental income goes up from April 2027, which changes the sums if you’re thinking of keeping your old home and letting it out.
- A new First Time Buyer ISA will replace the Lifetime ISA for new savers from April 2029, and the Lifetime ISA penalty for buying above £450,000 has been cut.
- The “mansion tax” is a yearly charge on homes in England worth £2 million or more, from April 2028.
Did stamp duty change in the 2026 Budget?
No. Stamp duty land tax in England stays exactly as it was. If you’re buying a home and it will be the only one you own, you pay:
| Part of the price | Rate |
|---|---|
| Up to £125,000 | 0% |
| £125,001 to £250,000 | 2% |
| £250,001 to £925,000 | 5% |
| £925,001 to £1.5 million | 10% |
| Above £1.5 million | 12% |
So on a £253,000 home you’d pay £2,650. On £295,000 it’s £4,750, and on £355,000 it’s £7,750.
First-time buyers
First-time buyer relief is unchanged too. There’s no stamp duty on the first £300,000, and 5% on the part between £300,001 and £500,000. Above £500,000 the relief doesn’t apply at all, and the standard rates kick in. Everyone buying with you has to be a first-time buyer for it to count.
If you’ll own more than one home
You usually pay an extra 5% on top of the standard rates if buying means you’ll own more than one home.
That can catch people out when they move house. If you buy your new home before your old one has sold, you pay the higher rates at completion. You may be able to claim the extra back if you sell your previous main home within 36 months, but you have to find the money first.
At The Mulberries, we pay it
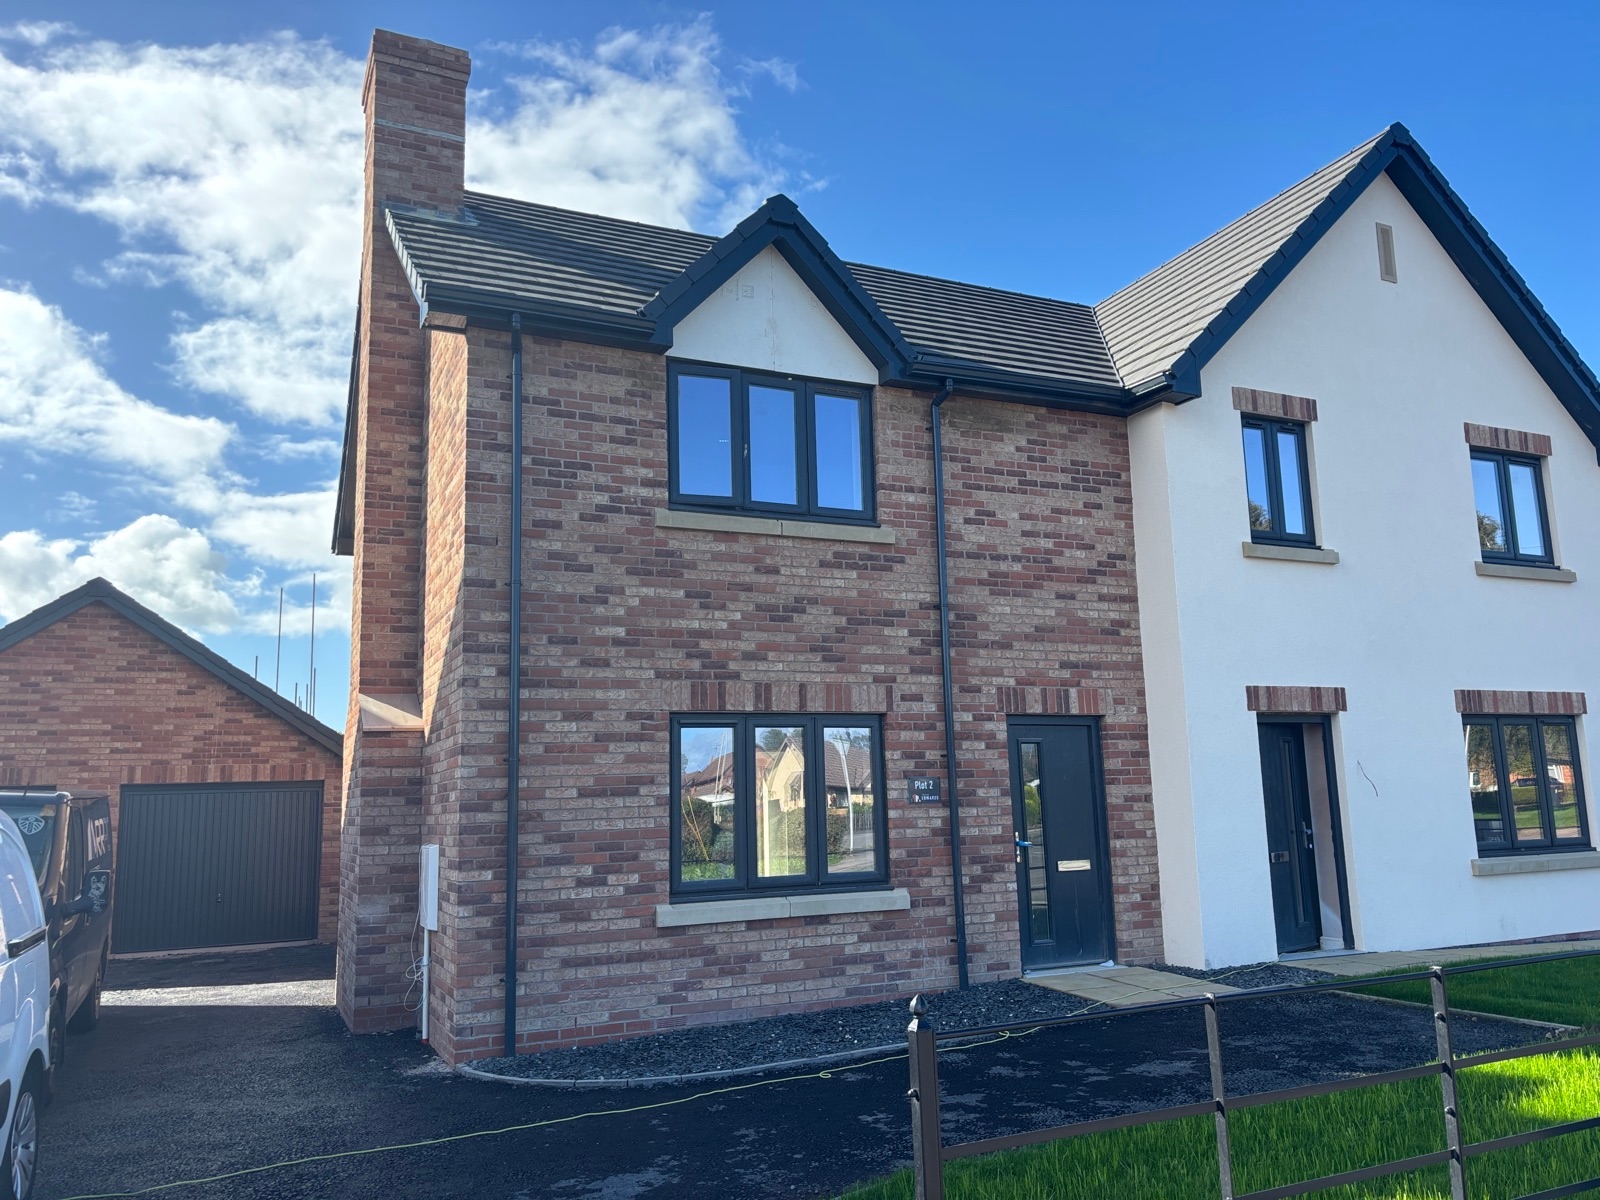
At the time of writing (4 November 2026), we pay the stamp duty on Plots 3 to 7 at The Mulberries at Dudleston Heath. On Plot 7, a finished three-bedroom detached Twyford at £355,000, that’s £7,750 at the standard rates. The offer is confirmed in writing when you reserve.
Thinking of keeping your old home and letting it out?
If you’re moving somewhere smaller, it’s tempting to keep the family home and rent it out. The Budget makes that harder to justify.
From 6 April 2027, income from property will be taxed at its own rates: 24% for basic-rate taxpayers, 44% at the higher rate and 49% at the additional rate. On top of that, you’d normally pay the extra 5% stamp duty on your new home, because you’d own two.
It’s worth running the numbers properly with your accountant before you decide. For plenty of people, selling will come out ahead.
If selling is the worry
For most people, the hard part of moving isn’t buying. It’s selling: finding a buyer, waiting on a chain, and hoping nobody pulls out.
That’s what part exchange is for. We buy your current home ourselves, so there’s no chain below you and no estate agent’s fee. On a £300,000 sale, a 1.5% agent’s fee would be £4,500. You stay in your home until your new one is ready, and you move once.
Your First Home: a 2.5% deposit on a new build
This was the Budget’s big housing announcement, with £4.7 billion behind it and an aim of helping 70,000 households buy their first home.
It’s an equity loan scheme for first-time buyers buying a new-build home in England. You put down at least 2.5%. The government lends you 20% of the price, and a mortgage covers the rest. On a £253,000 home, a 2.5% deposit is £6,325.
- The loan is interest-free for the first five years.
- Interest is 1.5% in year six and 3% from year seven.
- When you sell, you repay 20% of what the home is worth then, so the amount goes up or down with the market.
- Household income must be £110,000 or less (£140,000 in London).
- The home must be within a local price cap, and bought from a developer taking part in the scheme.
Pre-registration opens by the end of December 2026. Applications open in February 2027, and the first homes are expected to be bought from April 2027.
Two things are still to come. As of 4 November 2026, the price cap for Shropshire hasn’t been published, and registration for housebuilders hasn’t opened. We plan to register as soon as it does. The scheme only covers England, so it includes The Mulberries but not Wychwood at Four Crosses, which is just over the border in Wales.
We’ve written a fuller guide: A 2.5% deposit on a new-build home: how Your First Home works.
Saving for a first home: ISA changes
The Lifetime ISA penalty has been cut
The Lifetime ISA has a £450,000 price cap for first homes. Until now, using it to buy anything above that cost you a 25% withdrawal charge.
From 29 October 2026, first-time buyers buying a home above £450,000 pay a 20% charge instead. In effect, that takes back the 25% bonus, so you keep what you paid in. Buying at or under £450,000 is still charge-free.
A new First Time Buyer ISA from April 2029
From April 2029, a new First Time Buyer ISA replaces the Lifetime ISA for new savers.
- You can save up to £4,000 a year.
- The government adds a 25% bonus, up to £20,000 in total.
- The home price cap stays at £450,000.
- You can open one from 18, with no upper age limit.
Existing Lifetime ISAs carry on under their current rules. You can’t move a Lifetime ISA into the new account, but you can use both towards the same purchase.
The “mansion tax”: the High Value Council Tax Surcharge
The High Value Council Tax Surcharge is a yearly charge on top of normal council tax for homes in England worth £2 million or more, based on 2026 values. It’s paid by the owner, not the occupier, and starts in April 2028.
| Home value | Yearly charge |
|---|---|
| £2 million to £2.5 million | £2,500 |
| £2.5 million to £3.5 million | £3,500 |
| £3.5 million to £5 million | £5,000 |
| £5 million and above | £7,500 |
The charges rise with inflation each year from the 2029 to 2030 tax year. If your home is worth less than £2 million, it doesn’t apply.
What it means if you’re buying at The Mulberries
None of the Budget changes makes a new home at The Mulberries cost more to buy. Stamp duty is unchanged, and we pay it on Plots 3 to 7. If you have a home to sell, part exchange takes the chain out of it. If you’re a first-time buyer, Your First Home could bring a new build within reach from April 2027, once the Shropshire price cap is known.
Homes at The Mulberries range from two-bedroom semis to four-bedroom detached houses. Every one has an air-source heat pump, underfloor heating on the ground floor, an electric car charging point, and a 10-year LABC warranty alongside our own two-year warranty. You can read how the heating works in our guide, How our new homes are heated, and what happens between reserving and moving in, in Buying a new home at The Mulberries.
Come and see the homes
The sales office at The Mulberries is open on Saturdays and Sundays, 10am to 4pm, and you can just call in. Weekday viewings are by appointment.
The Mulberries, Dudleston Heath, Ellesmere, SY12 9LD. From Ellesmere, take the B5068 towards Dudleston Heath for about two miles. The Mulberries is on the left as you come into the village.
Book a viewing or call us on 01691 682 194.
Frequently asked questions
Did the 2026 Budget change stamp duty?
No. The rates and thresholds in England are the same as before the Budget, and so is first-time buyer relief.
How much stamp duty would I pay on a £300,000 home?
£5,000 if it’s the only home you’ll own and you’re not a first-time buyer. Nothing if everyone buying is a first-time buyer. If you’ll own another home as well, the extra 5% applies on top.
Is there stamp duty relief for downsizers?
There isn’t a separate relief for moving somewhere smaller. If you’re not a first-time buyer, you pay the standard rates in the table above, plus the extra 5% if you’ll own more than one home after the purchase. At The Mulberries, we pay the stamp duty on Plots 3 to 7.
When can I apply for Your First Home?
Pre-registration opens by the end of December 2026 and applications open in February 2027. The first homes are expected to be bought from April 2027.
Can I use Your First Home at The Mulberries?
The Mulberries is in England, so it can be included. Developers have to register for the scheme, and as of 4 November 2026 registration hasn’t opened. We plan to register as soon as it does. Which homes qualify will depend on the Shropshire price cap, which hasn’t been published.
Does the mansion tax affect homes in Shropshire?
Only homes worth £2 million or more, anywhere in England. It starts in April 2028.
Do you pay stamp duty on homes at The Mulberries?
Yes, on Plots 3 to 7 (correct at 4 November 2026). The offer is confirmed in writing when you reserve.
Can I use my Lifetime ISA and the new First Time Buyer ISA together?
Existing Lifetime ISAs carry on under their current rules and can’t be moved into the new account, but you can use both towards the same purchase.
Budget details are taken from the government’s announcements of 28 October 2026 and may change, particularly where final details are still to be published. This is a summary to help you plan, not tax or financial advice; speak to your solicitor, accountant or mortgage adviser about your own circumstances. Your home may be repossessed if you do not keep up repayments on your mortgage.
Sources: GOV.UK stamp duty rates, Budget 2026 overview of tax legislation and rates, High Value Council Tax Surcharge, Lifetime ISA withdrawal charge. Last reviewed 4 November 2026.